
What Is Zombie Debt? Definition, Examples, and How to Protect Yourself
What Is Zombie Debt?
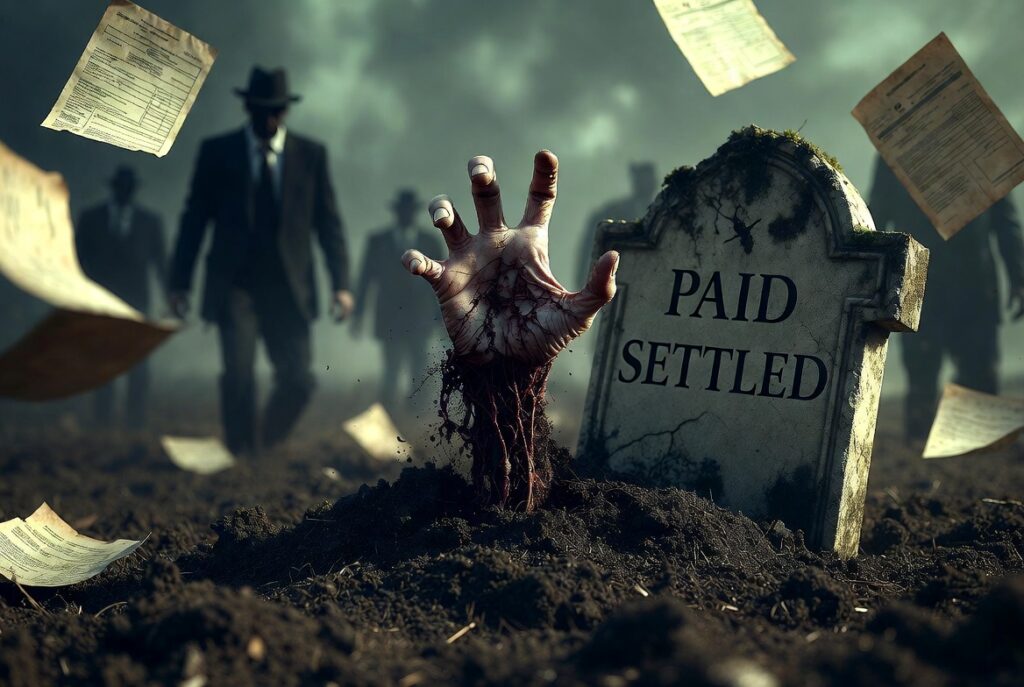
Zombie debt is old debt that has been largely forgotten—often because it is past the statute of limitations or was discharged in bankruptcy—but suddenly reappears when debt collectors attempt to collect it.
The term “zombie” is fitting because, like a zombie in a horror movie, this debt refuses to stay dead. It may rise from the grave years after it was written off, legally expired, or even settled, causing confusion, stress, and financial harm to consumers who may feel pressured to pay debts they no longer legally owe.
How Does Zombie Debt Happen?
Zombie debt typically arises through one of the following scenarios:
1. Debt Is Sold to Multiple Collectors
Original creditors often sell unpaid debts to collection agencies for pennies on the dollar. These agencies may resell the debt multiple times. Each new collector may attempt to collect the debt years later, often without accurate records of its age or status.
2. Statute of Limitations Has Expired
Every state has a statute of limitations on debt—a time limit (typically 3 to 10 years) during which a collector can sue you to collect. Once this period expires, the debt is “time-barred.” However, collectors may still attempt to collect, and if you make a payment or even acknowledge the debt, you may accidentally restart the clock.
3. Discharged Debt in Bankruptcy
If a debt was included and discharged in a bankruptcy filing, it is legally eliminated. Yet, collectors may still try to collect it years later, often due to poor record-keeping or intentional predatory practices.
4. Identity Theft or Clerical Errors
Sometimes, zombie debt is not even yours. It may result from identity theft, mistaken identity, or simple clerical errors where a collector confuses you with someone else with a similar name.
5. Debt Is Already Paid or Settled
You may have already paid off a debt, but the collector either lacks that record or intentionally ignores it, attempting to collect the same debt again.
Common Examples of Zombie Debt
| Scenario | How It Becomes Zombie Debt |
|---|---|
| Old credit card debt | A debt from 8 years ago (past statute of limitations) is sold to a new collector who demands payment with threats of a lawsuit. |
| Discharged bankruptcy | A medical bill that was included in a Chapter 7 bankruptcy resurfaced 3 years later with a new collection agency. |
| Paid-off loan | You paid off a car loan, but the paperwork was lost during a debt sale, and a collector now demands payment again. |
| Identity theft | A fraudulent account opened in your name goes to collections, and you are pursued for a debt you never incurred. |
| Relative’s debt | A collector contacts you for a deceased relative’s debt, even though you are not legally responsible. |
Your Legal Rights Against Zombie Debt
Under federal law, specifically the Fair Debt Collection Practices Act (FDCPA) , you have strong protections against abusive or deceptive debt collection practices.
1. You Have the Right to Debt Validation
Within 5 days of first contacting you, a debt collector must send a written notice with:
- The amount of the debt
- The name of the original creditor
- A statement of your right to dispute the debt
If you dispute the debt in writing within 30 days, the collector must stop collection efforts until they provide verification.
2. Time-Barred Debt Cannot Be Sued Upon
If the statute of limitations has expired, a collector cannot legally sue you for the debt. However, they may still attempt to collect. Important: Making a partial payment or even acknowledging the debt in writing may restart the statute of limitations in some states.
3. Discharged Bankruptcy Debt Is Void
If a debt was discharged in bankruptcy, it is permanently unenforceable. Collectors who attempt to collect discharged debt may be violating the Bankruptcy Code and can face sanctions.
4. Collectors Cannot Use Threats or Deception
The FDCPA prohibits collectors from:
- Threatening lawsuits they cannot legally file
- Falsely representing themselves as attorneys or government officials
- Harassing you with repeated phone calls
- Reporting time-barred debt to credit bureaus without disclosing its status
How to Handle Zombie Debt When It Appears
If you receive a collection notice for debt you believe is zombie debt, follow these steps:
Step 1: Do Not Pay or Admit Anything
Do not make a payment or acknowledge the debt in writing until you verify it. A partial payment can restart the statute of limitations and make you legally liable again.
Step 2: Request Debt Validation
Send a debt validation letter via certified mail within 30 days of receiving the initial notice. Request:
- Proof that you owe the debt
- The original creditor’s name
- Documentation showing the debt is within the statute of limitations
Step 3: Check the Statute of Limitations
Determine the statute of limitations for debt in your state. If the debt is older than that period, it is time-barred. You can inform the collector in writing that you will not pay because the debt is past the legal collection window.
Step 4: Check Your Credit Report
Review your credit reports from Equifax, Experian, and TransUnion at AnnualCreditReport.com. If zombie debt appears, dispute it immediately with the credit bureau and the collector.
Step 5: Cease and Desist
If you want all communication to stop, send a cease and desist letter requesting that the collector no longer contact you. Under the FDCPA, they must comply (except to inform you of a specific legal action).
Step 6: Consult an Attorney
If a collector sues you for zombie debt, do not ignore the lawsuit. Consult a consumer protection attorney. If they are violating the FDCPA, you may be entitled to $1,000 in statutory damages plus attorney’s fees.
Statute of Limitations by Debt Type
| Debt Type | Typical Timeframe |
|---|---|
| Credit card debt | 3–6 years (varies by state) |
| Medical debt | 3–6 years (varies by state) |
| Auto loan debt | 4–6 years (varies by state) |
| Personal loans | 3–6 years (varies by state) |
| Written contracts | 5–10 years (varies by state) |
| Oral contracts | 2–5 years (varies by state) |
Note: Statutes of limitations vary significantly by state. Always verify your specific state’s laws.
Zombie Debt vs. Valid Old Debt
| Zombie Debt | Valid Old Debt | |
|---|---|---|
| Status | Past statute of limitations, discharged, or already paid | Within statute of limitations; legally enforceable |
| Collector’s rights | Cannot sue; can only request payment | Can sue and obtain judgment |
| Consumer risk | Pressure tactics; accidental restart of clock | Legal liability; wage garnishment possible |
| Should you pay? | Generally no, unless you choose to settle (with caution) | Yes, or negotiate a settlement |
Frequently Asked Questions
Can zombie debt hurt my credit score?
Yes. If a collector reports the debt to credit bureaus, it can appear on your credit report and negatively impact your score. However, you have the right to dispute inaccurate or time-barred debts with the credit bureaus.
Can I go to jail for not paying zombie debt?
No. Debt collection is a civil matter, not a criminal one. You cannot be arrested or jailed for failing to pay consumer debt.
Should I pay zombie debt if a collector threatens to sue?
If the debt is past the statute of limitations, they cannot legally win a lawsuit. However, if they do sue, you must respond. Ignoring a lawsuit can result in a default judgment against you. Consult an attorney immediately.
How long does zombie debt stay on my credit report?
Most negative information, including collections, stays on your credit report for 7 years from the original delinquency date. If the debt is older than that, it should not appear. If it does, dispute it.
Can a collector restart the statute of limitations?
In many states, making a payment, entering a payment plan, or even acknowledging the debt in writing can restart the statute of limitations. Always verify your state’s laws before engaging with a collector on old debt.
Zombie debt can be alarming, especially when aggressive collectors use intimidating tactics. However, understanding your legal rights transforms you from a potential victim into an empowered consumer.
Key takeaways:
- Zombie debt is old, often unenforceable debt that resurfaces.
- Do not pay or acknowledge the debt without verifying it.
- Request debt validation in writing.
- Know your state’s statute of limitations.
- Report violations of the FDCPA to the Consumer Financial Protection Bureau (CFPB) and consider legal action if necessary.
Debt collectors rely on confusion and fear. By staying informed and asserting your rights, you can put zombie debt back in the grave—for good.
Disclaimer: This article is for educational purposes only and does not constitute legal advice. Laws regarding debt collection and statutes of limitations vary by state and jurisdiction. If you are facing a lawsuit or aggressive collection efforts, consult a qualified consumer protection attorney.

