
SpaceX Shares Hit Lows Before First Earnings Report: Musk Calls It an “Insane” Buying Opportunity
SpaceX stock has plunged more than 50% from its post-IPO high. Elon Musk calls it an “insane” buying opportunity ahead of the company’s first earnings report and a massive $100 billion lockup expiration.
A Volatile Ride Back to Earth
SpaceX (Nasdaq: SPCX) has had a breathtaking journey since its record-breaking IPO in June. After debuting at $135 per share and rocketing to an all-time high of $225.64, the stock has crashed back down to earth, falling more than 50% from its peak .
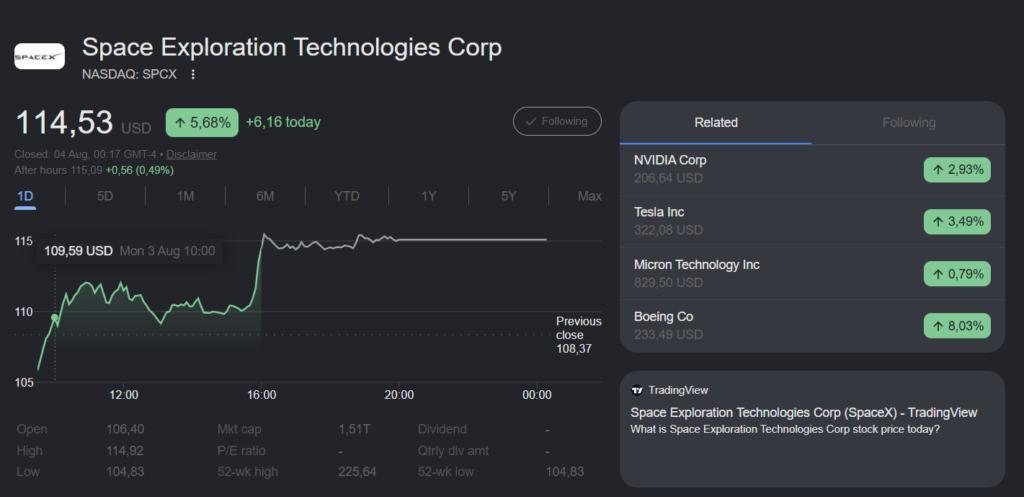
**The stock hit an all-time low of $104.83 on August 3, 2026**, before staging a late-day rebound to close near $114.53 . This dramatic sell-off comes just one day before the company is scheduled to report its first quarterly earnings as a public company .
But just before that late-day surge, Elon Musk weighed in. An investor posted that the dip would look like an “insane opportunity” in retrospect. Musk replied with three words: “I think so” .
Key Numbers: SpaceX Stock at a Glance
Why the Stock Is Falling: A Perfect Storm
The Lockup Expiration Looming
On August 6, 2026, a massive lockup restriction will expire, allowing early investors and employees to sell their shares for the first time . Up to 911.5 million shares — worth more than $100 billion at current prices — could hit the market, more than doubling the current tradable float .
This is a major overhang on the stock. As one analyst noted, “the lockup expiration is the bigger near-term test” . The new supply could outstrip demand in the short term, though some analysts point to Facebook’s 2012 lockup expiration, where shares actually rose 12.6% as holders refused to sell at depressed prices .
Unprofitable Business Burning Billions
SpaceX is not a traditional profitable company. The company posted a net loss of $4.9 billion in 2025** and a further **$4.28 billion loss in Q1 2026 . The business is burning billions of dollars a quarter as it invests heavily in Starship, Starlink, and AI infrastructure .
Wall Street expects Q2 revenue of roughly $6.85 billion, up from $4.7 billion in Q1, but still expects a loss of $0.19–$0.23 per share .
Capital Requirements and Debt
Analysts are concerned about SpaceX’s enormous capital spending. Capital expenditure is expected to increase from $48.7 billion in 2026 to **$118.4 billion by FY 2028**, while total debt could grow 5x from $41.7 billion to over $218 billion in the same period . This massive spending is needed to fund the orbital AI data center vision that accounts for 93% of the company’s stated market opportunity .
The Bull Case: Why Analysts See Opportunity
Despite the sell-off, Wall Street remains broadly bullish on SpaceX.
Analyst Price Targets
| Firm | Rating | Price Target | Upside (vs ~$115) |
|---|---|---|---|
| RBC Capital Markets | Outperform | $225 | ~96% |
| Morgan Stanley | Overweight | $300 | ~161% |
| Cantor Fitzgerald | Buy | $246 | ~114% |
| Bernstein | Buy | $239 | ~108% |
| New Street Research | Buy | $165 | ~43% |
The mean analyst price target implies the shares should more than double from current levels .
What Analysts Are Saying
New Street Research analyst Ben Harwood wrote: “For a long-term investor we think this is an attractive entry point. The growth runway is enormous, and SpaceX has one of the widest moats in the market today” .
Bernstein analysts advised clients that “the quarterly results should not matter. What will be important is the level of confidence projected by management regarding the company’s growth path” .
RBC Capital Markets believes the “recent pullback has created an attractive entry point, as investors remain focused on longer-term challenges while overlooking the company’s strong fundamentals and near-term business momentum” .
The AI Revenue Story
Much of SpaceX’s massive $1.4 trillion valuation rests on its AI business. In its IPO pitch, the company said AI accounts for **93% of its $28.5 trillion market opportunity** .
Huge AI Compute Deals
SpaceX has signed massive contracts to rent out data center capacity:
- Google: A deal worth $920 million per month to provide AI compute capacity
- Anthropic: A contract worth $1.25 billion per month through May 2029, totaling over $40 billion
- Reflection AI: A separate agreement to provide computing power
Cumulatively, these deals are expected to generate $28 billion in annual revenue .
The Q2 report will be the first time investors see actual financials from these contracts, including margins and profit contributions.
Retail Sentiment and Short Sellers
Short Selling Frenzy
Short sellers have been making massive profits from the decline. As of last week, shorts were up about $8.3 billion in paper profits since the IPO, according to S3 Partners . It has been described as “among the most aggressive and quickest bearish builds we have seen in a mega-cap name heading into its first earnings report post-IPO” .
Retail Sentiment Turns Bullish
Despite the bearish pressure, retail sentiment on Stocktwits has turned “bullish” from “neutral” ahead of the earnings report. One user noted that a “relief rally setup may be forming,” while another said they would not be surprised if the stock “blasts upwards on the unlock” .
Key Dates to Watch
Frequently Asked Questions
What is the SpaceX stock price?
SpaceX (SPCX) closed at approximately $114.53 on August 3, 2026, after hitting a low of $104.83, its lowest level since the IPO .
Why is SpaceX stock falling?
The stock has fallen due to a combination of profit-taking after the IPO, concerns about the August 6 lockup expiration, and the company’s massive spending and lack of profitability .
What is the lockup expiration?
The lockup expiration on August 6, 2026, allows early investors and employees to sell up to ~912 million shares for the first time, more than doubling the tradable float .
Is SpaceX profitable?
No. SpaceX posted a net loss of $4.9 billion in 2025 and a $4.28 billion loss in Q1 2026 .
What did Elon Musk say about SpaceX stock?
Musk replied “I think so” to an investor’s post suggesting that buying SpaceX at current levels would look like an “insane opportunity” in retrospect .
What is the analyst price target for SpaceX?
The mean analyst price target suggests the shares should more than double from current levels, with targets ranging from $165 to $300 .
Final Word
SpaceX is at a critical juncture. The stock has been cut in half from its post-IPO high, a massive lockup expiration looms, and the company burns billions of dollars a quarter. Yet analysts remain overwhelmingly bullish, and Elon Musk himself has called the current price an “insane” buying opportunity.
For long-term investors willing to stomach the volatility, the growth runway is enormous. SpaceX is uniquely positioned across launch, connectivity, and AI, with one of the widest moats in the market. But the near-term path is uncertain, with a flood of new shares potentially hitting the market on August 6.
As one analyst noted, whether the stock can stabilize will depend on management’s ability to project confidence in the company’s growth path — and whether holders refuse to sell at these depressed prices.
Key takeaways:
- Stock at lows: SPCX hit $104.83, down 50%+ from its peak
- Lockup risk: ~912 million shares free to sell August 6
- Analyst bullish: Mean price target suggests more than double
- Musk endorsement: Called it an “insane” opportunity
- AI revenue: Massive Google and Anthropic deals driving growth
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Stock market investing involves significant risk. Always conduct your own research or consult a licensed financial advisor before making investment decisions.

